Flagged by the Algorithm: When AI Fraud Detection Freezes the Wrong Account
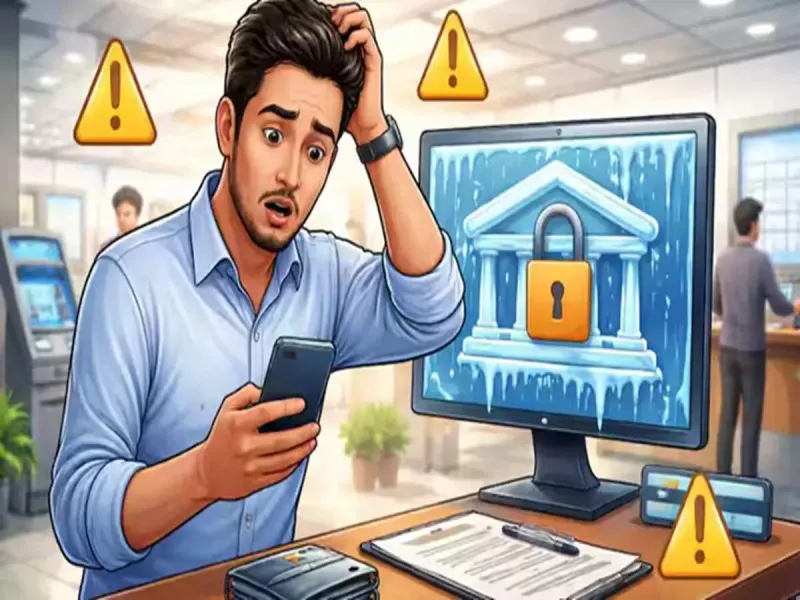
Photo: person on phone with bank customer service account frozen computer screen, via gyanhigyan.com
Imagine your debit card declining at a grocery store checkout. You call your bank, and the representative tells you your account has been flagged for suspicious activity and temporarily restricted. You have not traveled internationally, made any unusual purchases, or done anything that would register as out of the ordinary — at least, not to you. To an algorithm processing millions of transactions per second, however, something in your behavioral pattern deviated enough from a statistical baseline to trigger an automated hold. Welcome to the false-positive crisis in AI-driven fraud detection.
Financial institutions in the United States collectively lose tens of billions of dollars annually to payment fraud. The deployment of machine-learning systems to identify and block fraudulent transactions in real time has been one of the industry's most effective countermeasures. But effectiveness at scale comes with a cost that is rarely discussed in bank press releases: a meaningful percentage of the transactions these systems flag are entirely legitimate, and the customers behind them are left to navigate an appeals process that is frequently opaque, slow, and designed with the institution's liability concerns — not the customer's convenience — as the primary consideration.
How AI Fraud Detection Actually Works
Modern fraud-detection systems are trained on enormous datasets of historical transaction behavior. They learn to identify patterns associated with fraud: unusual geographic locations, atypical purchase categories, transaction velocity that exceeds a customer's established norms, device fingerprints inconsistent with prior sessions, and dozens of other variables. When a transaction or account activity crosses a risk threshold, the system triggers an automated response — which can range from a soft decline requiring step-up verification to a full account freeze.
The sophistication of these models has increased dramatically. Banks now incorporate behavioral biometrics (how you type, swipe, or hold your phone), network analysis linking accounts to known fraud rings, and real-time cross-institutional data sharing through networks like Early Warning Services, which operates the Zelle payment infrastructure.
The problem is inherent to how these systems are built. They are optimized to minimize fraud losses, not to minimize false positives. A model that catches 99 percent of fraud while incorrectly flagging one percent of legitimate transactions may look excellent on a performance dashboard — but when a bank processes millions of transactions daily, that one percent represents a substantial number of real customers experiencing real financial disruption.
The Human Cost of Algorithmic Error
Consumer complaints filed with the Consumer Financial Protection Bureau paint a consistent picture. Account holders describe having direct deposits frozen — sometimes for days — leaving them unable to pay rent or utilities. Small business owners report having merchant accounts suspended during peak operating periods, with no advance notice and no clear timeline for resolution. Elderly customers describe being unable to access funds for medical expenses while waiting for identity verification processes that require document uploads through mobile apps they struggle to navigate.
Zelle-related disputes have been particularly contentious. Because many banks initially characterized authorized-push-payment fraud as the customer's responsibility — even when the customer was manipulated into initiating a transfer — the line between fraud victim and fraud suspect has sometimes blurred in ways that compound harm for people who have already been victimized.
The appeals process at most major institutions requires customers to contact a fraud department, verify their identity through channels the bank specifies, and then wait for a manual review that can take anywhere from 24 hours to ten business days. During that window, the customer's access to their own funds may be partially or completely restricted.
Disparate Impact: Who Gets Flagged Most
Research from academic institutions and consumer advocacy organizations has documented a troubling pattern: AI fraud-detection systems do not distribute false positives evenly across the population. Several factors contribute to disparate impact.
Transaction pattern diversity. Customers whose spending habits, geographic range, or financial behavior diverge from the statistical majority are more likely to trigger anomaly-detection systems. This can disproportionately affect recent immigrants, gig-economy workers with irregular income patterns, and individuals who frequently send remittances internationally.
Thin-file customers. Consumers with limited banking history — often younger adults, lower-income households, or those who have recently transitioned from cash-based financial lives — provide less behavioral baseline data for models to work with. Counterintuitively, less data can mean higher risk scores, because the system has less evidence that a given transaction is consistent with established behavior.
Geographic and demographic proxies. While reputable institutions take steps to avoid explicit demographic variables in fraud models, ZIP code, merchant category, and behavioral patterns can function as proxies that encode demographic disparities present in training data. This is a well-documented problem in algorithmic fairness research that the financial industry has not fully resolved.
The CFPB has flagged concerns about discriminatory outcomes in automated financial decision-making, and several state banking regulators have opened examinations into the fairness of AI-driven account management systems. Federal guidance on algorithmic accountability in banking remains a developing area, and enforcement has been inconsistent.
Your Rights When an Algorithm Freezes Your Account
Consumers have more recourse than many realize, though exercising those rights requires persistence.
Request a specific explanation. Under the Equal Credit Opportunity Act and related regulations, institutions are required to provide specific reasons for adverse actions on credit accounts. For deposit account restrictions, the regulatory framework is less prescriptive, but most institutions have internal policies requiring some level of explanation. Ask explicitly: what triggered the flag, and what is required to resolve it.
Escalate beyond the front-line representative. Initial fraud-department contacts are often limited in their authority to reverse automated decisions. Request escalation to a supervisor or a dedicated account review team. Document the name of every representative you speak with and the time and date of each contact.
File a CFPB complaint. Submitting a complaint through the CFPB's consumer portal (consumerfinance.gov/complaint) creates a formal record and requires the institution to respond. The CFPB's complaint database is public, and institutions are aware that unresolved complaints affect their supervisory relationships with regulators. This step frequently accelerates resolution.
Contact your state banking regulator. For state-chartered banks and credit unions, the relevant state regulator has authority over consumer complaint handling. A directory of state regulators is maintained by the Conference of State Bank Supervisors.
Consider a formal dispute letter. For restrictions tied to a specific transaction dispute, the Fair Credit Billing Act and the Electronic Fund Transfer Act provide specific dispute rights with defined timelines for institutional response. A written dispute letter sent via certified mail creates a paper trail and triggers statutory obligations.
Maintain an emergency fund at a second institution. This is perhaps the most practical protective measure available. Holding a modest emergency reserve at a separate bank or credit union ensures that a single institution's algorithmic decision does not produce complete financial paralysis.
A Calibration Problem Without an Easy Fix
The tension between fraud prevention and customer experience is unlikely to resolve itself quickly. Financial institutions face genuine regulatory and financial consequences for fraud losses; they face comparatively softer consequences for false positives that inconvenience customers. Until that incentive structure shifts — through stronger regulatory requirements around false-positive rates, transparency mandates, or meaningful penalties for discriminatory algorithmic outcomes — the burden of navigating these systems will continue to fall disproportionately on customers.
For consumers, the most effective posture is an informed one: understand that these systems exist and can affect anyone, know what rights you hold before you need to exercise them, and maintain the kind of financial redundancy that limits the damage any single algorithmic error can cause. The algorithm does not know you. That is precisely why you need to know how to fight back.